Short Answer
A roof insurance claim starts when you document damage and submit a claim. Contractors provide photos, repair estimates, and scope letters, while the insurer reviews your policy and sends an adjuster to decide coverage. Next safe step: document everything and schedule a professional inspection.
Key Takeaways
- Document damage thoroughly (photos, dates, receipts) before repairs.
- Contractors prepare scope and estimates; the insurer decides coverage and payment.
- Local weather and roof age affect claim outcomes in Greater Pittsburgh and Western Pennsylvania.
- Book a Free Drone Inspection for clear documentation and a no-pressure estimate.
How a Roof Insurance Claim Works
A roof insurance claim typically follows three practical steps: document the damage, file a claim with your insurer, and let the insurer evaluate coverage. Your contractor documents scope and estimated repairs; the insurer evaluates your policy, inspects (often with an adjuster), and issues a coverage decision. You and your contractor then agree on repairs or next steps.
What homeowners should look for
Start with clear, dated photos and notes. Capture overall roof condition, close-ups of missing shingles, dents, leaks, and interior signs like water stains. Save receipts for emergency repairs or temporary tarps. Keep communication in writing when possible: emails and photos timestamped on your phone help a lot.
Checklist: What to document before, during, and after a claim
- Date and time of the storm or event
- Wide-angle photos of the whole roof
- Close-up photos of damaged areas, shingles, gutters, vents
- Interior photos of leaks or stains in attic and ceilings
- Receipts for temporary fixes (tarping, emergency repairs)
- Any contractor estimates or scope letters
Contractor documentation vs. insurer decision
| Who provides it | What it contains | What it affects |
|---|---|---|
| Contractor documentation | Photos, repair scope, materials & labor estimate, roof condition notes | Helps insurer understand needed repairs and supports your claim |
| Insurer decision | Policy review, adjuster’s inspection, coverage determination, payout calculation | Determines whether and how much the insurer will pay under your policy |
Contractors do not decide coverage; they document and recommend repairs. Insurers interpret policy language and determine covered losses.
What changes the answer in Western Pennsylvania
Weather and housing stock in Greater Pittsburgh and Western PA make claims more common during certain seasons. Heavy snow, ice dams, wind, and occasional hail can cause roof damage. Older homes with original roofing or multiple layers of shingles may have different repair needs and replacement costs, which can affect your contractor’s scope and the insurer’s assessment.
Local factors to consider
- Snow and ice: Ice dams and repeated freeze-thaw cycles can cause leaks that may be gradual rather than immediate.
- Wind: Wind-driven shingle loss can be obvious after a storm.
- Hail: Hail can bruise shingles without removing them; documentation and professional inspection matter.
- Older roofs: Some policies limit payouts for roofs past a certain age or for roofs with prior wear.
Always review your actual policy language or ask your insurer about age and wear considerations.
Options, tradeoffs, and common mistakes
Options
- File a full claim: Good for major, clear storm damage. May lead to higher out-of-pocket if your deductible or premium impact is a concern.
- Make a small repair out of pocket: May be faster and avoid filing a claim, but only safe if the damage is minor and won’t worsen.
Tradeoffs
- Filing a claim can bring funds for repairs but may affect future premiums depending on your insurer.
- Waiting to repair can lead to bigger problems if the damage gets worse.
Common mistakes
- Not documenting damage immediately (photos and receipts).
- Making large repairs before the insurer or an adjuster sees the damage (except for emergency tarps).
- Relying solely on verbal promises: get estimates and communications in writing.
When to call a roofing professional
Call a pro when you see missing shingles, obvious leaks, or after a significant storm. In Greater Pittsburgh and Western Pennsylvania, snow and wind events can hide damage until spring thaw. A roofing professional can provide a clear scope, safety-first assessment, and a no-pressure estimate or honest recommendations to support your claim.
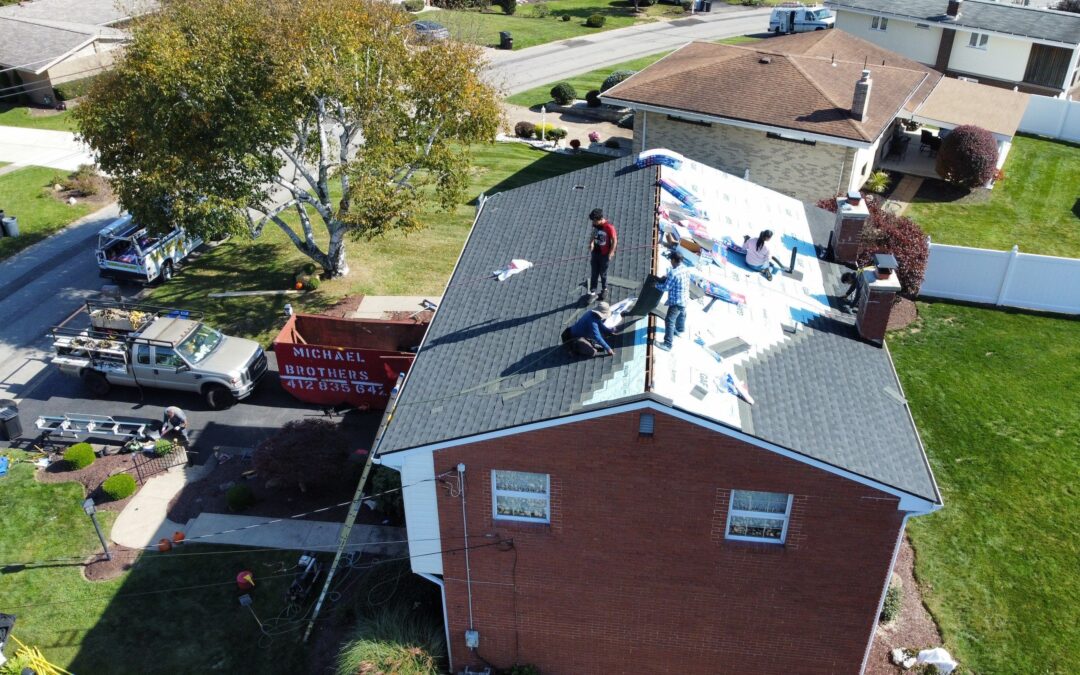
Mid-article note: Want reliable, timestamped documentation? Book a Free Drone Inspection to capture high-resolution images of your roof safely. We provide a no-pressure estimate and clear documentation you can use with your insurer.
Final takeaway
A roof insurance claim is a two-part reality: contractors document and estimate repairs while insurers interpret policy language and decide coverage. In Greater Pittsburgh and Western Pennsylvania, local weather, roof age, and prompt documentation matter. Stay organized, document everything, and get a professional inspection before making major repair decisions.
Book a Free Drone Inspection
If you suspect storm damage or want strong documentation to support a claim, Book a Free Drone Inspection with Big Fish Roofing. We’ll provide clear photos, a no-pressure estimate, and honest recommendations tailored to your Greater Pittsburgh or Western Pennsylvania home.
Frequently Asked Questions
What are the main steps in a roof insurance claim?
Document the damage, report the loss to your insurer, complete the requested inspection, review the coverage decision, and coordinate the approved repairs. Follow the notice and documentation requirements in your policy.
Should I repair the roof before the adjuster sees it?
Take reasonable emergency steps to prevent additional damage, such as temporary tarping when it can be done safely. Keep photos and receipts, and ask your insurer before authorizing permanent repairs that could remove evidence.
Who decides whether roof damage is covered?
The insurance company decides coverage based on the policy and its investigation. A roofing contractor can document conditions and prepare a repair scope, but cannot promise that a claim will be covered.
What records should I keep during the claim?
Keep dated photos, inspection notes, estimates, receipts, claim numbers, and written communications with the insurer and contractor. Organized records make it easier to compare the approved scope with the work the roof needs.
Talk With Big Fish Roofing
Big Fish Roofing serves Greater Pittsburgh and Western Pennsylvania with clear, customer-first guidance. Book a Free Drone Inspection or ask for a no-pressure estimate to discuss your property.