Short Answer
Filing a roof claim may affect future premiums or underwriting, but there is no universal outcome. The result depends on the insurer, the cause and size of the loss, prior claim history, regional risk, policy terms, and applicable rating or underwriting rules.
Key Takeaways
- A roof claim does not automatically produce the same premium change for every homeowner.
- Insurers may consider claim frequency, severity, cause, property condition, and regional loss trends.
- A written roof inspection and estimate can help you compare documented repair costs with your deductible.
- A contractor documents roof condition, scope, and cost; the insurer decides coverage, pricing, and underwriting.
How a Roof Claim Can Affect Your Premium
A roof claim premium increase is possible, but it is not guaranteed. Some insurers may change a renewal price, deductible, eligibility, or coverage terms after reviewing claim history and property risk. Other claims may not cause an immediate change. Ask the insurer or licensed agent for policy-specific information before making assumptions.
The cause matters as well. A sudden wind or hail event is evaluated differently from deterioration, faulty installation, or maintenance-related damage. The policy language and documented facts determine how the insurer evaluates coverage.
Factors Insurers May Consider
- Claim history: the number, timing, and type of prior claims associated with the property or policyholder.
- Loss severity: the documented repair cost and amount paid after the deductible.
- Cause of damage: whether the reported condition resulted from a covered event or an excluded cause.
- Roof condition: age, materials, maintenance, prior repairs, and remaining service life.
- Regional risk: local storm frequency, weather losses, construction costs, and insurer experience.
- Company rules: each insurer applies its approved rating and underwriting standards.
Checklist Before Filing
- Review the deductible and relevant policy conditions.
- Document the damage date, discovery date, and visible conditions.
- Obtain a property-specific inspection and itemized repair estimate.
- Compare the documented repair cost with the deductible.
- Ask the insurer or licensed agent how a reported claim may be handled.
- Preserve photos, receipts, and records of temporary protection.
What Changes in Western Pennsylvania
Greater Pittsburgh and Western Pennsylvania properties face freeze-thaw cycles, wind, hail, heavy rain, snow, and older housing stock. Insurers may evaluate these conditions alongside broader regional loss experience and the individual property’s roof age and maintenance history.
Local construction costs and the availability of matching materials can also influence a repair estimate. These factors do not predict a specific premium or coverage decision; they help explain why outcomes can vary among properties and insurers.
Options, Tradeoffs, and Common Mistakes
Homeowners generally compare the documented repair cost, deductible, timing requirements, and need for prompt loss notice before deciding how to proceed.
- Pay out of pocket: avoids seeking claim payment but requires the homeowner to cover the full repair cost.
- Report the loss: starts the insurer’s claim process and preserves a documented notice, subject to policy terms.
- Request more information first: an inspection and estimate can clarify condition and cost, but should not be used to ignore a policy’s notice duties.
Common mistakes include assuming the insurer will make a particular pricing decision, relying on a contractor for coverage advice, delaying documentation, or filing without comparing the repair estimate and deductible.
Decision Factors to Compare
| Factor | What to review | Why it matters |
|---|---|---|
| Repair estimate | Itemized scope and property-specific cost | Helps compare the loss with the deductible |
| Deductible | Amount and whether a special wind or hail deductible applies | Affects potential out-of-pocket cost |
| Notice requirements | Policy conditions and insurer instructions | Late notice may complicate review |
| Claim history | Recent reported losses and outcomes | May be considered in pricing or underwriting |
When to Call a Roofing Professional
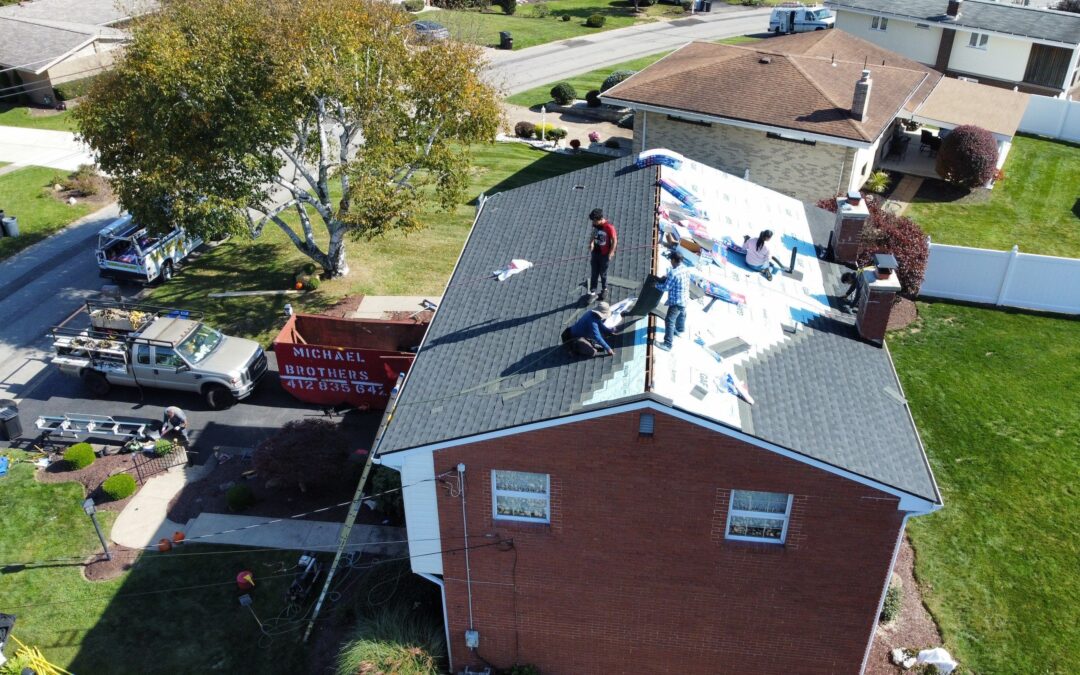
Contact a qualified roofer when you see missing shingles, active leaks, displaced flashing, impact marks, or other changes after a storm. A roofer can safely inspect the property, document visible conditions, and prepare an itemized repair estimate.
A contractor should not promise insurance coverage, claim payment, or a specific premium outcome. The contractor’s role is to document roof condition, likely repair scope, measurements, and costs. The insurer makes the coverage and underwriting decisions.
If you need clear property documentation in Greater Pittsburgh or Western Pennsylvania, book a free drone inspection for a no-pressure assessment.
Frequently Asked Questions
Does every roof claim increase the premium?
No. There is no universal result. The insurer may consider the loss, prior claims, property risk, regional conditions, policy terms, and its approved rating and underwriting rules.
Can a denied or zero-payment claim still appear in claim history?
A reported loss may still be recorded even if the insurer denies coverage or pays nothing. Ask the insurer or licensed agent how the report will be documented and considered.
Should I get an estimate before filing?
A timely inspection and estimate can help you understand the condition, repair scope, cost, and deductible comparison. It should not delay notice when the policy requires prompt reporting.
Can an insurer decline renewal after roof claims?
Underwriting decisions vary by insurer, claim history, property condition, and applicable rules. Ask for a written explanation of any renewal decision and contact the Pennsylvania Insurance Department if you need consumer assistance.
Talk With Big Fish Roofing
Big Fish Roofing serves Greater Pittsburgh and Western Pennsylvania with clear, customer-first guidance. Book a Free Drone Inspection or ask for a no-pressure estimate to discuss your property.