Short Answer
An insurer may require roof replacement as a condition of continuing or renewing coverage, even when there is no claim. After a covered loss, the insurer may separately determine that replacement is necessary under the policy and approved scope. A roofer can document roof condition and costs, but the insurer decides coverage and underwriting requirements.
Key Takeaways
- An insurer’s decision depends on your specific policy, not just the contractor’s report.
- Contractors document damage and recommend repairs; insurers decide coverage and payout.
- In Greater Pittsburgh and Western Pennsylvania, storm, wind, and age are common factors.
- Get a professional inspection, photos, and a no-pressure estimate before filing a claim.
What homeowners should look for
To understand why an insurer may require roof replacement, look at two separate things: the roof condition and the policy language.
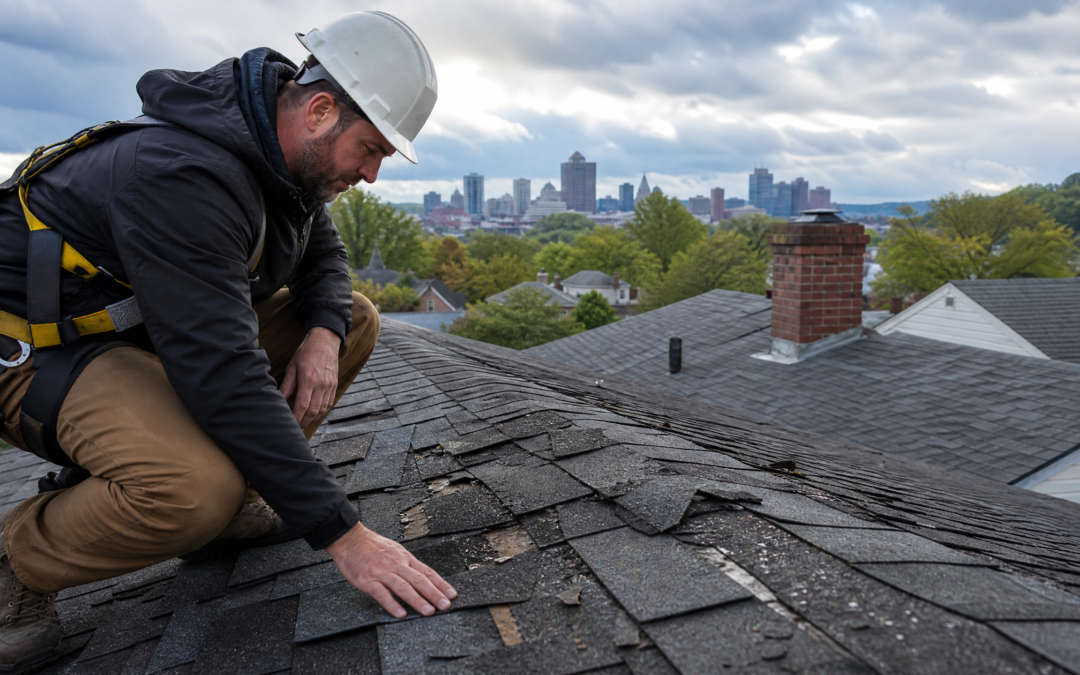
- Roof condition: missing shingles, widespread granule loss, sagging, or structural damage suggest larger problems. Document with photos and a dated inspection report.
- Policy language: check terms for “actual cash value” vs “replacement cost”, hurricane or wind exclusions, and the deductible. Coverage depends on the policy, not just the contractor’s recommendation.
Keep records: inspection reports, photos, repair estimates, and any communication with your insurer. That documentation helps you and your adjuster evaluate the claim.
What changes the answer in Western Pennsylvania
Greater Pittsburgh and Western Pennsylvania homes face specific factors: frequent freeze-thaw cycles, strong wind storms, heavy sleet, and older housing stock. These factors can accelerate wear and lead insurers to conclude a roof is beyond repair—if the damage meets policy definitions of a total loss or widespread failure.
Local notes for homeowners:
- Age matters: insurers often weigh the roof’s age when deciding if replacement is necessary.
- Weather history: recent wind, hail, or ice events help support a claim when damage aligns with the event.
- Regional contractors: choose roofers familiar with local codes and common wear patterns in Western PA.
Options, tradeoffs, and common mistakes
When facing potential replacement, homeowners usually choose between repair or replacement. Here’s a quick comparison:
| Option | When it makes sense | Tradeoffs |
|---|---|---|
| Repair | Isolated, minor damage (few shingles, small leaks) | Lower cost now, may need future repairs if underlying issues remain |
| Replace | Widespread damage, structural issues, or roof near end of life | Higher upfront cost, longer-term protection, may affect claims payoff under policy |
Common mistakes to avoid:
- Waiting too long to document damage: storms fade from memory and evidence can be lost.
- Accepting a verbal estimate: get written documentation and a no-pressure estimate.
- Assuming contractor recommendations equal insurer approval—contractor documentation supports your claim but doesn’t guarantee coverage.
Checklist: Documents to gather before filing a claim
- Photos of all visible damage (dated)
- Roof inspection report from a licensed roofer
- Written repair or replacement estimate (itemized)
- Your insurance policy declarations page and recent renewal
- Receipts for any temporary repairs
Documentation note: If you’re unsure what the roof damage looks like from the ground, Book a Free Drone Inspection with Big Fish Roofing. We provide clear, documented footage and a no-pressure estimate so you can make informed decisions and present solid documentation to your insurer.
When to call a roofing professional
Call a roofing professional if you notice active leaks, large areas of missing shingles, sagging, or after a severe storm. In Greater Pittsburgh and throughout Western Pennsylvania, quick documentation matters: a qualified roofer can provide an inspection report, photos, and a realistic no-pressure estimate that clarifies repair vs. replacement needs.
A roofer can also explain whether repairs are likely to be a short-term fix or if replacement is the more economical long-term choice. This helps you decide what to present to your insurer and what your out-of-pocket options might be.
Final takeaway
An insurer can require a roof replacement when the damage meets your policy’s definition of a loss, but that decision is separate from what a contractor documents. Get a licensed roofer’s inspection, detailed photos, and a no-pressure estimate to support your claim and make the best decision for your home in Greater Pittsburgh or anywhere in Western Pennsylvania.
Frequently Asked Questions
Can an insurance company require roof replacement without a claim?
An insurer may make roof replacement a condition of continuing or renewing coverage because of age, condition, or underwriting rules. The written notice should explain the reason, deadline, and any coverage changes.
What can happen if I do not replace the roof?
Depending on the policy and applicable notice rules, the insurer may decline renewal, change terms, or limit roof coverage. Ask for the decision in writing and contact the Pennsylvania Insurance Department if you need help understanding your options.
Is a roof replacement requirement the same as claim approval?
No. An underwriting requirement concerns whether the insurer will continue offering coverage. A claim decision concerns whether a specific loss is covered under the policy. A roofing contractor can document condition and costs but cannot decide either issue.
What records should I request from the insurer?
Request the written notice, inspection findings or photos, the policy language or endorsement supporting the requirement, the compliance deadline, and any appeal or reinspection instructions. Keep your own contractor assessment and estimates with those records.
Talk With Big Fish Roofing
Big Fish Roofing serves Greater Pittsburgh and Western Pennsylvania with clear, customer-first guidance. Book a Free Drone Inspection or ask for a no-pressure estimate to discuss your property.